
If an uninsured driver hits you in Texas, your main options are your own uninsured motorist (UM) coverage, personal injury protection (PIP), health insurance, and a lawsuit against the driver. UM coverage is usually the strongest path, but your own insurer will evaluate the claim like an opponent. Review your policy and get legal advice before giving statements or signing anything.
Reviewed by David Burkett, personal injury trial attorney, 40 years representing injured people in Corpus Christi and across Texas. Last legally reviewed October 2026.
Being hit by an uninsured driver in Texas is more common than most people expect, and it leaves injured people asking the same question: who pays now? The answer largely depends on the coverage you may already have on your policy. This guide walks through each option, how Texas law treats uninsured and underinsured drivers, and the mistakes that can reduce or delay your recovery.
How Common Are Uninsured Drivers in Texas?
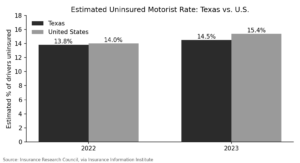
Texas requires every driver to carry liability insurance of at least $30,000 per injured person, $60,000 per accident, and $25,000 for property damage, often written as 30/60/25. Even so, a significant share of Texas drivers are on the road without coverage. According to Insurance Research Council estimates published by the Insurance Information Institute, about 14.5 percent of Texas motorists were uninsured in 2023, roughly one in seven drivers.
Driving without insurance is illegal in Texas and can lead to fines starting at $175 for a first offense, plus license and registration consequences. But penalties against the other driver do not pay your medical bills. That is why understanding your own coverage matters so much.
Option 1: Uninsured Motorist (UM) Coverage
Uninsured motorist coverage steps in for the at-fault driver’s missing insurance. Under the Texas Insurance Code, every insurer that sells auto liability coverage in Texas must offer UM and underinsured motorist (UIM) coverage, and you can only decline it by signing a written rejection. If you don’t have a written rejection, you may have UM coverage even if you don’t remember choosing it.
UM bodily injury coverage can pay for medical expenses, lost wages, pain and suffering, and mental anguish up to your policy limits. UM property damage coverage can pay for repairs to your vehicle, typically subject to a $250 deductible. In many cases, UM coverage also protects you and your resident family members as pedestrians, cyclists, or passengers in another person’s car.
There is one important catch. Even though you are filing against your own policy, your insurance company does not automatically accept your version of events. To recover UM benefits, you generally must show that the other driver was at fault and was uninsured or underinsured, and you must prove the amount of your damages. In that sense, your insurer evaluates the claim much like the other driver’s insurer would.
Option 2: Underinsured Motorist (UIM) Coverage
Many Texas drivers carry only the 30/60/25 minimum. If you suffered a serious injury, $30,000 may not come close to covering hospital bills, surgery, and months away from work. Underinsured motorist coverage pays the difference between the at-fault driver’s liability limits and your actual damages, up to your own UIM limits.
Before you accept a settlement from the other driver’s insurer, read your policy carefully. Many policies require you to notify your insurer and obtain its consent before settling with the at-fault driver. Settling too quickly can put your UIM claim at risk.
Option 3: Personal Injury Protection (PIP)
Texas insurers must also offer personal injury protection coverage of at least $2,500 per person, and like UM coverage, it can only be rejected in writing. PIP is no-fault coverage, which means it pays regardless of who caused the crash. It can cover medical bills and a portion of lost income for you and passengers in your vehicle.
PIP benefits are usually paid faster than a UM claim and can help with immediate costs while the larger claim is evaluated. Using PIP does not prevent you from pursuing UM benefits or a claim against the at-fault driver.
Option 4: Health Insurance and Other Benefits
Your health insurance, Medicare, or Medicaid can cover treatment while your injury claim is pending. Keep in mind that these plans may have a right to be reimbursed from any later settlement, so those liens must be identified and negotiated at the end of the case. If the uninsured driver was intoxicated or fled the scene, you may also be eligible for help through the Texas Crime Victims’ Compensation Program administered by the Office of the Attorney General.
Option 5: Suing the Uninsured Driver Directly
You can file a personal injury lawsuit against an uninsured driver, and the deadline for most of these cases is two years from the crash under the Texas personal injury statute of limitations. The challenge is collection. Many uninsured drivers have few assets, and winning a judgment does not guarantee payment. A lawsuit can still make sense when the driver has assets, was driving a vehicle owned by someone else, or was working for an employer at the time of the crash.
What If It Was a Hit-and-Run?
Texas policies generally treat an unidentified hit-and-run driver as an uninsured motorist. Standard policy language, however, typically requires actual physical contact between the hit-and-run vehicle and you or your vehicle. If a driver ran you off the road without touching your car, you may have to dispute coverage. Call police immediately, report the crash to your insurer promptly, and save any dashcam footage, surveillance video, or witness contact information you can find.
Comparing Your Coverage Options
| Source of Payment | Fault Required? | What It Typically Covers | Key Limitation |
|---|---|---|---|
| Uninsured motorist (UM) | Yes, other driver must be at fault | Medical bills, lost wages, pain and suffering, vehicle damage | Limited to your policy limits; insurer can dispute fault and damages |
| Underinsured motorist (UIM) | Yes | Damages above the at-fault driver’s limits | May require insurer consent before settling with the other driver |
| Personal injury protection (PIP) | No | Medical bills and part of lost income | Lower limits, often $2,500 to $10,000 |
| Health insurance | No | Medical treatment | Deductibles apply; plan may seek reimbursement |
| Lawsuit against the driver | Yes | All damages proven in court | Collecting the judgment may be difficult |
Steps to Protect Your Claim
- Call 911 and make sure a police report is filed, especially if the other driver admits to having no insurance or tries to leave.
- Get the other driver’s name, license number, plate number, and vehicle information, along with photos of the scene and contact details for witnesses.
- See a doctor promptly, even if you feel fine, and follow through on all recommended treatment.
- Notify your insurer of the accident as your policy requires, but avoid giving a detailed recorded statement about your injuries before talking with a lawyer.
- Request a copy of your full policy, including the declarations page and any signed rejection forms for UM, UIM, or PIP coverage.
- Keep records of medical bills, missed work, mileage to appointments, and how your injuries affect daily life.
Our checklist of things to do after a car accident covers these steps in more detail, and if your injuries have caused anxiety, sleep problems, or fear of driving, you may also want to read about whether you can recover for emotional distress.
What David Burkett Tells Clients About Uninsured Driver Claims
“People are surprised when their own insurance company starts acting like the other side. You paid your premiums for years, and now the adjuster is questioning whether you were really hurt or whether the other driver was really at fault. A UM claim is still an injury claim, and it has to be proven the same way. The first thing we do is get the full policy, confirm what coverage is actually there, and make sure nothing is signed or settled that could close the door on the rest of the claim.” David Burkett, The Burkett Law Firm
Your insurance company has adjusters working to limit what it pays. You deserve someone working for you. The Burkett Law Firm helps people across Texas pursue uninsured and underinsured motorist claims and makes sure every available source of coverage is identified. [Insert verified case result here.] Call (361) 882-8822 to talk with our team.
Frequently Asked Questions
Is uninsured motorist coverage required in Texas?
No. Texas insurers must offer uninsured and underinsured motorist coverage with every auto liability policy, but you can reject it. The rejection must be in writing. If you never signed a written rejection, the coverage may be part of your policy even if you do not remember buying it.
Does uninsured motorist coverage apply to a hit-and-run in Texas?
It can. Texas policies generally treat an unidentified hit-and-run driver as an uninsured motorist, but standard policy language usually requires actual physical contact between the hit-and-run vehicle and you or your vehicle. Report the crash to police right away and keep any photos, video, or witness information.
What does uninsured motorist coverage pay for?
UM bodily injury coverage can pay for the same kinds of damages you could recover from an at-fault driver, including medical bills, lost wages, pain and suffering, and mental anguish, up to your policy limits. UM property damage coverage can pay for vehicle repairs, usually after a $250 deductible.
What if the other driver had insurance, but not enough?
That is where underinsured motorist (UIM) coverage comes in. After the at-fault driver’s liability limits are exhausted, your UIM coverage can pay the difference up to your own policy limits. Check your policy before settling with the other driver’s insurer, because many policies require your insurer’s consent first.
Can I sue an uninsured driver personally?
Yes. You can sue the at-fault driver and obtain a judgment. The practical problem is collecting it, since many uninsured drivers have limited assets. That is why your own UM, UIM, and PIP coverage are usually the most reliable sources of payment.
How long do I have to act after a crash with an uninsured driver?
You generally must file a lawsuit against the at-fault driver within two years of the crash. Your policy also requires prompt notice of the accident and of any UM claim, and missing those requirements can create problems with your own insurer. It is best to notify your insurer and talk with a lawyer early.
Does my UM coverage protect me if I am a passenger or pedestrian?
Often, yes. Texas UM coverage typically follows you and resident family members, not just your car. If you are hit as a pedestrian, a cyclist, or a passenger in someone else’s vehicle, your own UM coverage may apply in addition to any coverage on the vehicle you were in.
Common Concerns About Hiring a Lawyer for a UM Claim
“It is my own insurance company. Why would I need a lawyer?” Because the insurer’s financial interest is to pay as little as possible, even to its own customer. Insurers use the same claim-evaluation tools for UM claims as they do for strangers, and they may argue about fault, the cost of treatment, or whether an injury was preexisting.
“My claim is small. Is it worth it?” It may be. If you are unsure, our guide on whether you need a lawyer for a Corpus Christi car accident explains when legal help tends to make the biggest difference. A free consultation can also tell you how much coverage is available before you decide.
“I cannot afford an attorney.” The Burkett Law Firm handles injury claims on a contingency fee basis. There are no upfront costs, and we are paid only if we recover compensation for you.
What to Expect When You Call The Burkett Law Firm
When you call, a member of our team will ask how the crash happened, what you know about the other driver’s insurance, what injuries and treatment you have had, and what coverage you carry. If you have your policy declarations page, keep it handy. The consultation is free, and you will come away knowing which coverage options likely apply to your situation and what to avoid while your claim is pending.
Talk to a Texas Personal Injury Lawyer About Your Options
An uninsured driver should not leave you paying for someone else’s mistake. The Burkett Law Firm has represented injured Texans for decades from our Corpus Christi office. Learn more about our Corpus Christi personal injury lawyers, call (361) 882-8822, or contact us online for a free consultation. [Insert verified case result here.
